✓
Organize evidence
Part of the water damage claims assistance in florida | skyfold restoration workflow, handled in a safety-first sequence.
General documentation support for restoration-related insurance conversations without promising coverage decisions.
Water-loss response depends on the source, duration, affected materials and safe access to the property.
Part of the water damage claims assistance in florida | skyfold restoration workflow, handled in a safety-first sequence.
Part of the water damage claims assistance in florida | skyfold restoration workflow, handled in a safety-first sequence.
Part of the water damage claims assistance in florida | skyfold restoration workflow, handled in a safety-first sequence.
Part of the water damage claims assistance in florida | skyfold restoration workflow, handled in a safety-first sequence.
Protect people first, avoid unsafe electrical conditions, document the visible loss and seek appropriate restoration support.
Keep people away from dangerous areas and call 911 for immediate hazards.
Stop the water source only when doing so can be done safely.
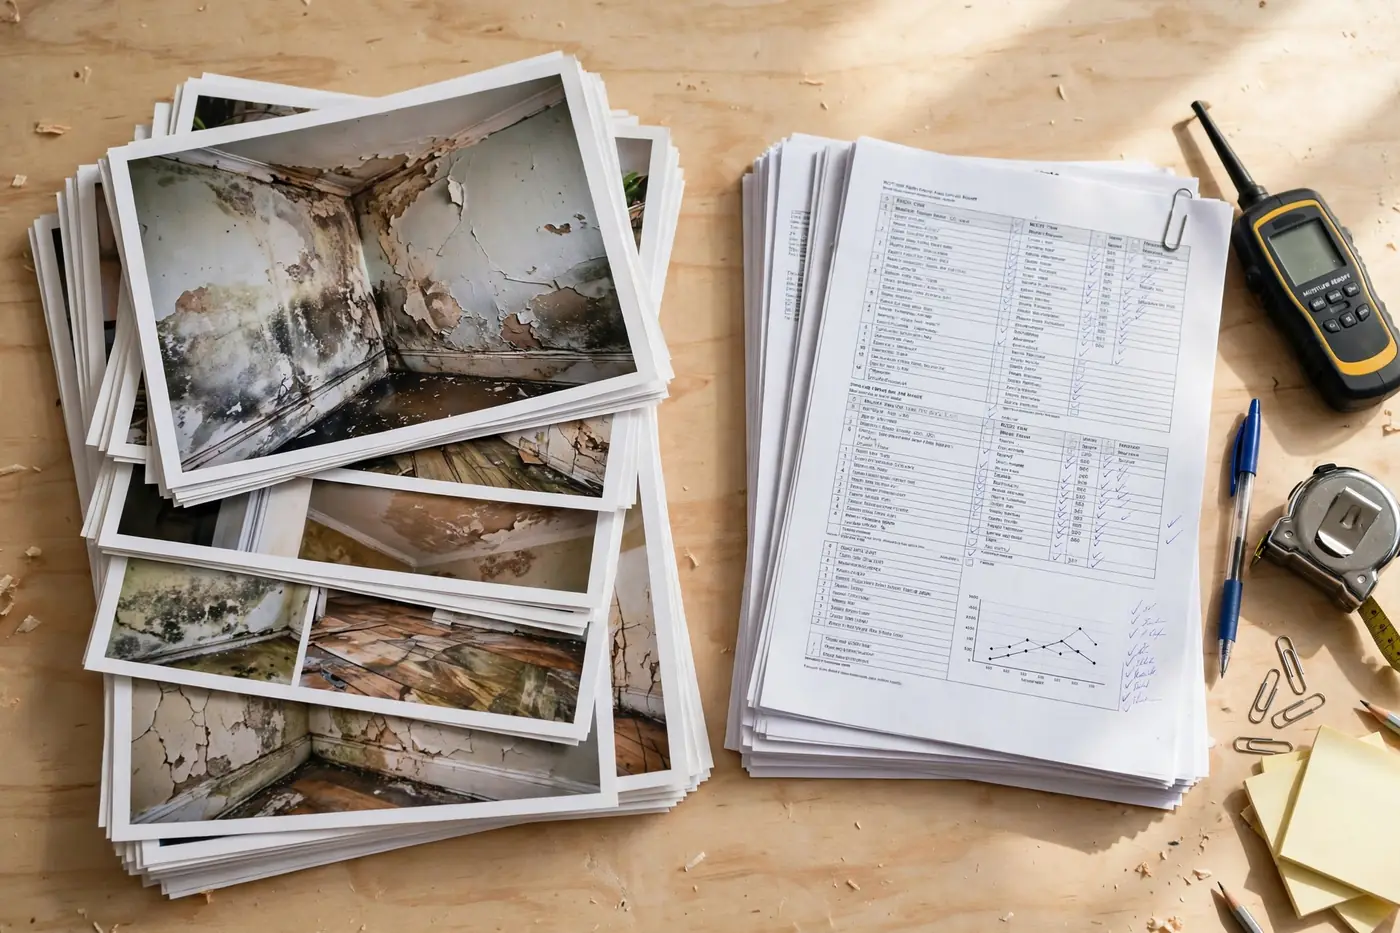
Photograph visible damage and record the time, source and affected areas.
Move toward water removal, drying and moisture monitoring as soon as appropriate.
Coordinated assessment, extraction, drying and cleanup after a water loss.
View pageRapid response pathways for active or spreading water damage.
View pageStanding-water removal and immediate moisture control.
View pageEquipment-based drying and moisture monitoring for affected materials.
View pageCleanup and drying planning after flood-related water intrusion.
View pageRemoval of unwanted water from accessible residential and commercial spaces.
View pageIn Florida water damage claims, one distinction decides more outcomes than any other: sudden and accidental versus gradual damage. A burst pipe, a failed supply line, or an appliance overflow that happens all at once is the classic covered loss. A slow drip inside a wall that continues for weeks or months, wear and tear, and deterioration from deferred maintenance are typically excluded, often under policy language about continuous or repeated seepage over 14 days or more.
This is where many claims are won or lost. Insurers sometimes classify a loss as gradual to deny it, but under Florida's all-risk homeowners policies the burden of proof sits with the insurer: you show direct physical loss, and the carrier must prove the exclusion applies. Strong rebuttal evidence includes a plumber's report identifying the failure point, moisture meter readings and thermal imaging showing the water's path, a clear written timeline, and maintenance records proving the system was cared for.
Related boundaries matter too. Mold coverage is frequently capped by fungi sublimits well below actual remediation cost. Sewer backup usually needs a separate rider. And flood, meaning rising water from outside, is excluded from standard policies entirely. Our Florida insurance coverage guide breaks down each of these, and if your loss came from a pipe failure specifically, see burst pipe water damage for the documentation that supports sudden-loss classification.
Florida law sets hard deadlines on water damage claims, and missing them can end your claim regardless of its merits. Since legislative changes in December 2022, you have one year from the date of loss to report a new or reopened claim, and 18 months for supplemental claims. These are strict cutoffs, not guidelines.
Once you report, the clock runs on the carrier too. Florida's Homeowner Claim Bill of Rights requires acknowledgment within 14 days, regular status updates, and a pay or deny decision within 90 days of notice, with a 60-day pay-or-deny clock running after required documentation is received. Late payments can accrue 12 percent annual interest. If you disagree with the outcome, a presuit notice process exists before litigation.
Practically, this means three things. Report promptly, ideally within days, since late reporting is a common denial trigger. Never wait for the adjuster before starting emergency mitigation: your policy requires you to prevent further damage, and the 24 to 48 hour mold window does not pause for paperwork. Document everything from the first hour using our insurance documentation checklist and emergency checklist, because the paper trail you build now is what enforces every deadline later.
Call the existing Skyfold Restoration number or submit the request form with the property address and what happened.